By Appbay Technologies
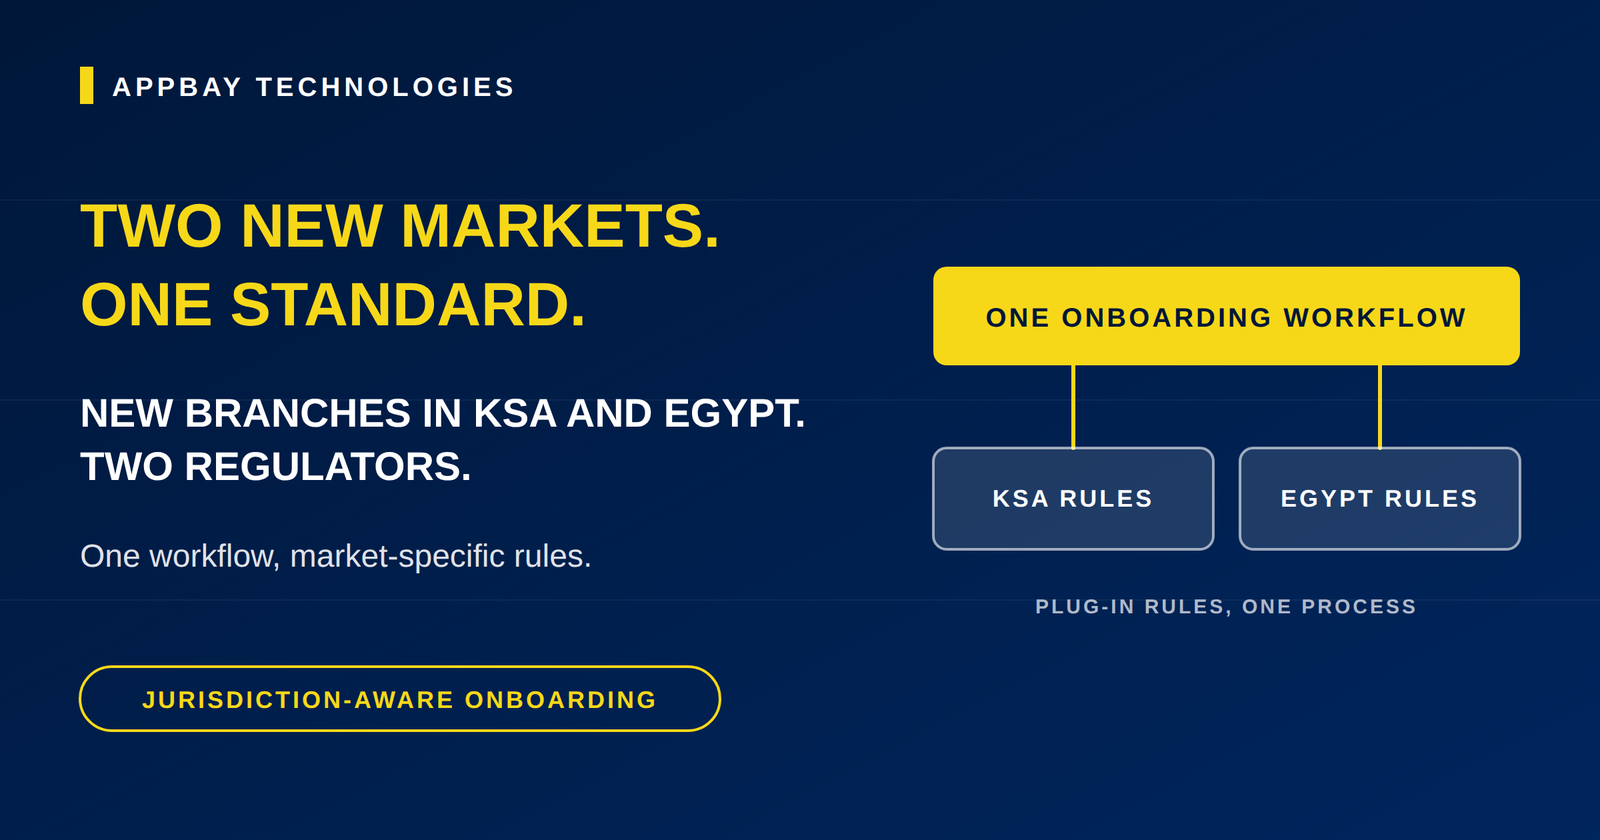
A subsidiary makes the headline. Onboarding clients across jurisdictions, without loosening review, is the work that follows.
A Lebanese bank is expanding its wealth management services through a French subsidiary to serve diaspora clients. A named subsidiary aimed at a named client group signals clear intent. It also creates a queue: every client file has to satisfy more than one jurisdiction before the client can be funded.
This piece is a candid one. The fit is a good one with some configuration work, and we’ll be specific about which parts are which.
The Priority: Growing Wealth Services for Diaspora Clients
Expanding wealth management for clients who live abroad is a clear and worthwhile priority. It is also a competitive one, where speed matters, because a diaspora client has options.
That creates a real operational question: can a bank onboard a cross-border wealth client quickly without weakening its KYC, source-of-wealth, and suitability review?
The Hidden Problem: Review Capacity That Doesn’t Scale
Here’s where the operational gap can show up, inside a bank onboarding cross-border wealth clients:
- Residency documents re-requested – clients asked again for proof they have already supplied
- Source-of-wealth proof chased – evidence gathered file by file from several countries
- Suitability forms redone – the same assessment repeated as a file moves between teams
- Clients waiting to fund – each new client queued behind manual review
Why does this exist? Cross-border wealth clients carry more documentation and more regulatory touchpoints than domestic ones. Demand grows with the client base, but review across jurisdictions grows with analysts. When documents arrive in varied formats from several countries, and checks against each jurisdiction’s requirements are applied case by case, the compliance team becomes the pacing item for the whole subsidiary.
Why This Matters Now
The subsidiary was built for diaspora wealth. When does each client pay back?
The board backed the expansion. It now wants time-to-revenue and cost per client on the next pack. The question that follows isn’t rhetorical:
“How quickly does a new client start earning, and what did it cost to onboard them?”
For the Head of Wealth, the COO, and the CCO, this plays out across four measures:
- Time-to-revenue per client – how long between first approach and first revenue
- Cost per onboarded client – the real cost of each onboarding, across both jurisdictions
- Subsidiary revenue versus plan – how the subsidiary tracks against its promise
- Diaspora client revenue versus plan – whether the target segment earns as expected
Without that visibility, subsidiary growth is capped by onboarding capacity.
An Honest Look at the Fit
We want to say this plainly: this is a good fit, with configuration work. Client onboarding with KYC and suitability review is close to Appbay’s core strength. Appian suits the workflow directly: intake, risk-tiered routing, review, approval, and audit trail.
What transfers directly:
- Document intelligence for client files
- Audit IQ-style auditable reporting for every decision
What is configuration work, not a ready product:
- Encoding each jurisdiction’s own requirements, which the bank’s compliance team has to define
- Integration with the subsidiary’s systems
Interpretation of regulation, risk appetite, and every approval stay with the bank. AI supports the analysis and does not make the call.
Here’s what that would actually involve:
Ingest Client Documents
Files brought into one governed workflow, whichever country they come from.
AI Extraction and Checking Against Jurisdiction Rules
Documents checked against each market’s requirements, with gaps flagged early.
Auto-Route by Risk Tier
Straightforward files move through quickly. Complex ones reach the right officer with the evidence already assembled.
Compliance Officer Approval
Every approval remains with a person.
Full Audit Trail
Every step and decision on record, in a consistent format across jurisdictions.
The practical starting point is a scoped 8-12 week proof of concept on one client segment and one jurisdiction pair, for example diaspora clients onboarding into the French subsidiary, rather than all wealth clients at once. It would show whether risk-tiered onboarding shortens time-to-fund without loosening review.
Why We’re Saying This Plainly
Being specific matters more than a broad claim would. This problem sits close to what Appbay already builds, so the honest message is that we can scope it clearly, and that encoding each jurisdiction’s rules is configuration work that depends on the bank’s own compliance team. Naming that up front is more useful than overstating it.
This Pattern Isn’t Unique to One Bank
Any institution serving cross-border wealth clients will face the same constraint: demand grows with the client base, but review across jurisdictions grows with analysts. The banks getting ahead of this treat risk-tiered onboarding as part of the subsidiary’s design from the start, and prove it on one segment first.
Let’s Compare Notes
We’re curious how other banks are onboarding cross-border wealth clients faster without loosening review. If your organization is working through the same challenge, we’d welcome the conversation.
Send us a message. This one’s genuinely about comparing notes, not a pitch.