By Appbay Technologies
A partner platform makes the headline. Keeping checks fast and sound once the branch counter is gone is the work that follows.
A Palestinian Islamic bank now takes financing requests from a partner platform and returns offers digitally. For micro, small and medium enterprises, that is a real step toward easier access to finance. It also changes where the work happens: the branch counter used to handle identity, documents and explanation in one place.
This piece is a candid one. The fit is partial, with the workflow side close to what we build and the Islamic-product side depending on the bank’s own rules, and we’ll be specific about which is which.
The Priority: Digital Channels and Access to Finance
Advancing digital transformation, widening access to MSME financing and doing it through a partner platform are clear and worthwhile priorities. They also create a practical question: when an applicant never visits a branch, where do the checks happen?
That raises a real operational question: can a bank answer each platform request quickly without weakening identity, document and product checks?
The Hidden Problem: Work Spread Where the Counter Used to Be
Here’s where the operational gap can show up, inside a bank taking requests from a platform:
- Documents chased remotely – proof requested repeatedly with no one across the counter
- Platform data re-keyed – details from the partner’s system retyped into the bank’s own
- Remote identity checks – verification done without meeting the applicant
- Requests with missing proof – applications that arrive incomplete and wait
Why does this exist? Requests arrive from a third-party channel and have to be matched to the bank’s own Sharia-compliant products, checked remotely and answered with an offer. A platform removes the counter that did identity, documents and explanation in one place, and that work lands on several steps and teams instead. Funding partners also tend to expect evidence tied to individual financings, which adds a reporting task on top.
Why This Matters Now
The platform is live. What does each financing request cost to answer?
The board backed digital channels. It now wants cost per request and time-to-offer on the next pack. The question that follows isn’t rhetorical:
“Is the platform lowering what each request costs us, or only moving the work out of the branch?”
For the COO and the Head of SME Financing, this plays out across four measures:
- Cost per financing request – what each request costs once checking effort is counted
- Time-to-offer – how long an applicant waits for an answer
- Request-to-financing conversion – how many requests become financings
- Partner reporting line – what the bank can show the platform and its funding partners
Without that visibility, requests pile up behind remote document chasing, offers return slowly, and cost per request stays high just as digital volume is meant to grow.
An Honest Look at the Fit
We want to say this plainly: this is a partial fit, with configuration work.
What transfers directly:
- Appian for intake, routing and approval
- Document intelligence for applicant files
- Audit IQ-style auditable reporting for every decision
- LoanSphere for the origination and decision workflow
What is configuration work, not a ready product:
- The bank’s Islamic financing products and their eligibility rules
- Contract and Sharia-review steps
- The interface with the partner platform
- Integration with the core system
Islamic-product logic in particular may need new accelerator work. Sharia decisions, credit decisions and risk appetite stay with the bank. AI supports the checking and does not make the call.
Here’s what that would actually involve:
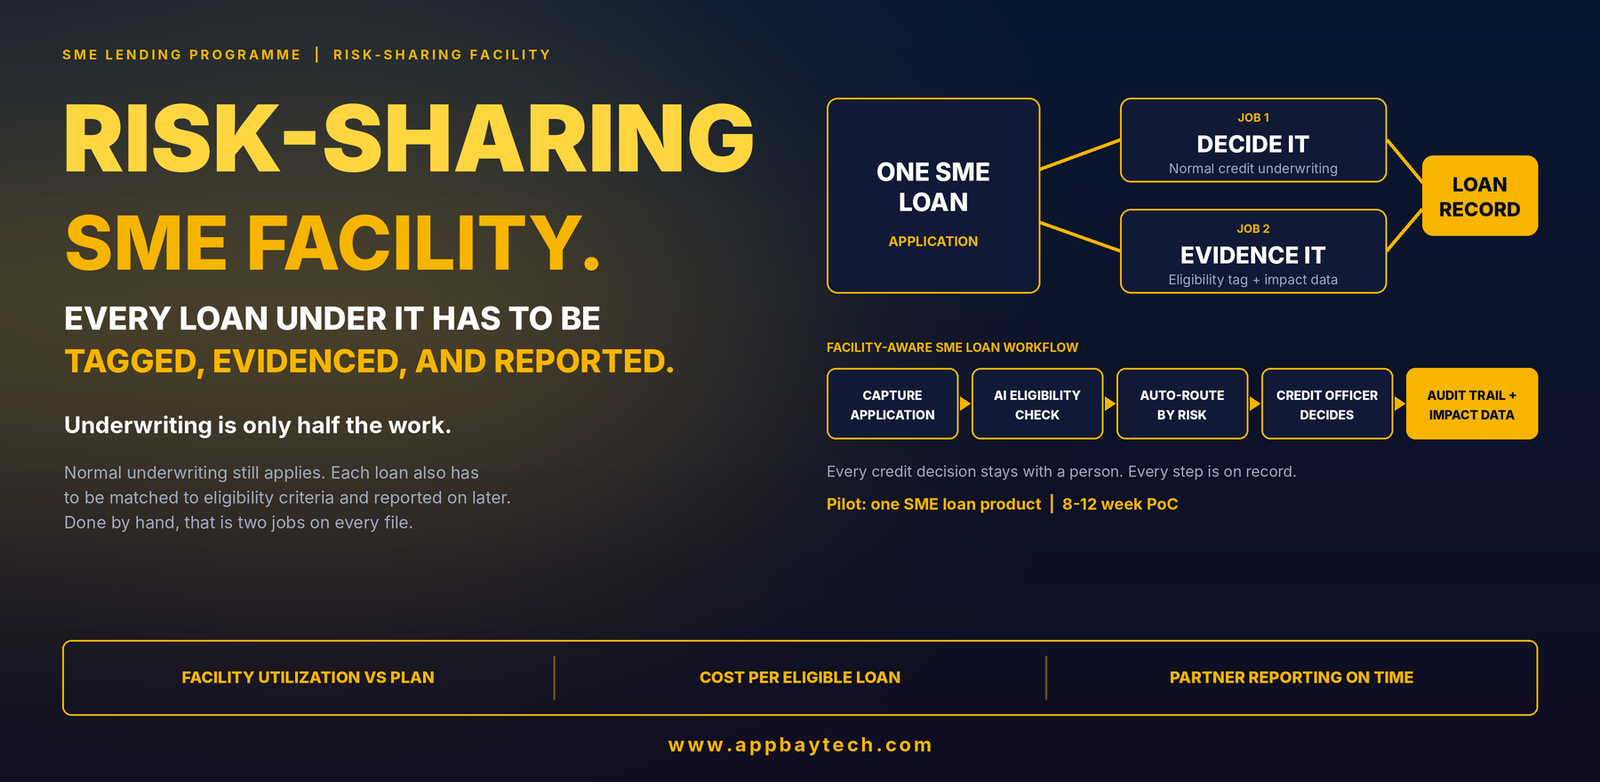
Request Arrives From the Platform
Requests brought into one governed workflow, rather than re-keyed.
AI Reads Documents and Data
Applicant files and platform data checked as they arrive, with missing proof flagged at intake.
Auto-Route by Product and Risk
Each request reaches the right team with the evidence already assembled.
Sharia and Credit Officers Approve
Every decision remains with a person.
Offer Returned, Audit Trail Kept
Every step and decision on record, which also supports partner reporting.
The practical starting point is a scoped 8-12 week proof of concept on one financing product from one platform. It would show whether reading and routing proof at intake shortens time-to-offer without loosening checks. It would not cover every product, and extending it would be a larger conversation about scope.
Why We’re Saying This Plainly
Being upfront matters more here than a confident pitch would. The intake, routing and approval workflow is close to what we build. The Islamic financing rules, the Sharia-review steps and the partner interface depend on the bank’s own products and systems, and some of that is new work. Naming that clearly and starting with one product is more useful than overstating the fit.
This Pattern Isn’t Unique to One Bank
Any institution opening a partner channel will face the same constraint: the applicant never visits, but identity, documents, product matching and approval still have to happen. The banks getting ahead of this read and route proof at intake, with a person approving at the end, and prove it on one product first.
Let’s Compare Notes
We’re curious how other banks are answering partner-platform financing requests without slowing checks. If your organization is working through the same challenge, we’d welcome the conversation.
Send us a message. This one’s genuinely about comparing notes, not a pitch.